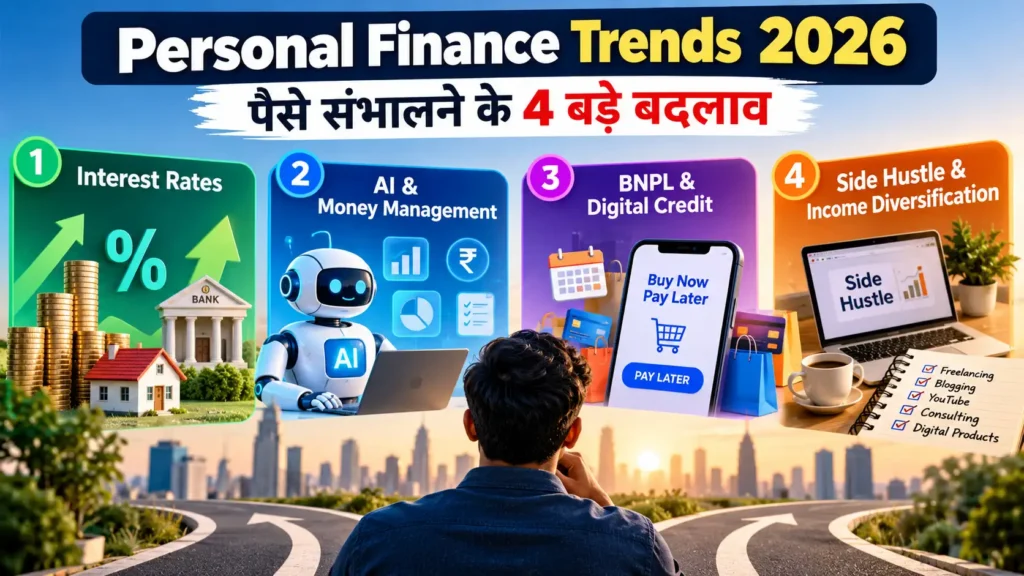
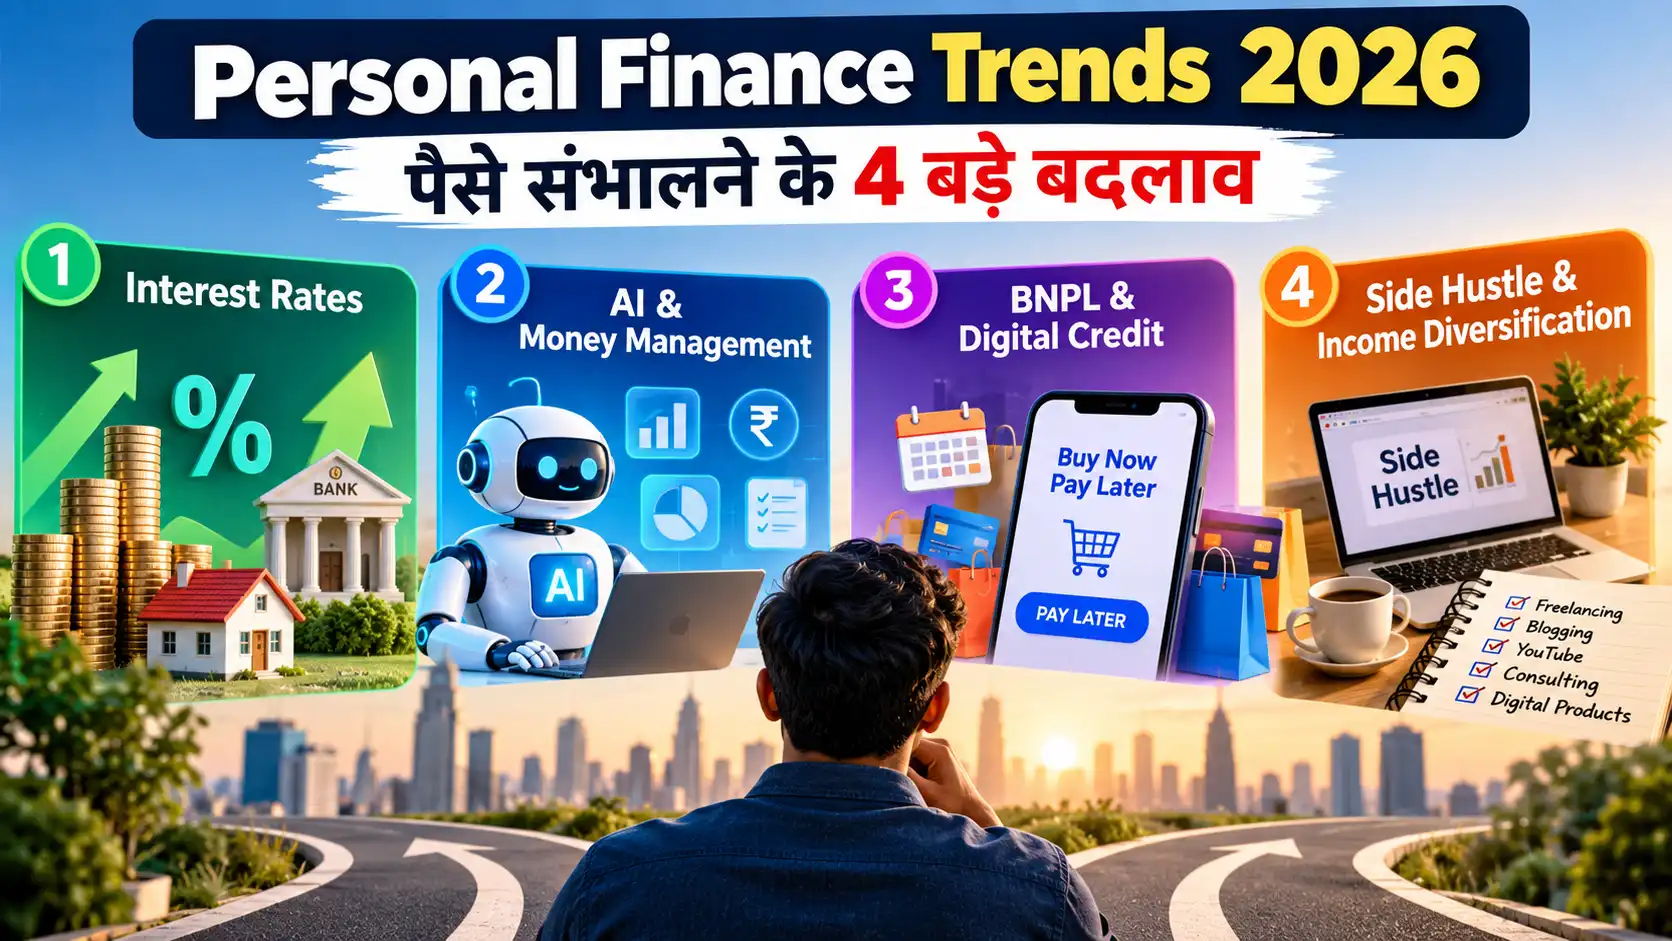
Personal Finance Trends 2026: पैसे संभालने के 4 बड़े बदलाव
2026 में Personal Finance की दुनिया पहले से ज्यादा digital और technology-driven हो गई है। AI, digital payments, digital lending, बदलती interest rates और income के नए तरीकों ने लोगों के पैसे संभालने के तरीके को प्रभावित किया है।
लेकिन इसका मतलब यह नहीं है कि पुराने financial products या saving habits बेकार हो गए हैं। असली बदलाव यह है कि अब लोगों के सामने money management के ज्यादा विकल्प हैं और उनके साथ कुछ नए risks भी जुड़े हैं।
इसलिए Personal Finance Trends 2026 in Hindi को समझने का मतलब किसी एक investment या financial product को चुनना नहीं है। इसका मतलब है कि बदलते financial environment को समझकर अपनी planning को बेहतर तरीके से व्यवस्थित करना।
इस लेख में हम 2026 के चार महत्वपूर्ण Personal Finance trends को आसान भाषा में समझेंगे और देखेंगे कि इनका आपकी financial planning पर क्या असर पड़ सकता है।
Table of Contents
2026 में Personal Finance क्यों बदल रहा है?
कुछ साल पहले तक Personal Finance का मतलब मुख्य रूप से income, expenses, savings, FD और investment से जोड़ा जाता था। आज इसके साथ digital payments, online banking, digital credit, AI tools और income diversification भी जुड़ गए हैं।
Technology ने financial services को ज्यादा accessible बनाया है, लेकिन सुविधा के साथ financial decisions की जिम्मेदारी भी बढ़ी है। इसलिए 2026 में सिर्फ पैसा कमाना या बचाना ही पर्याप्त नहीं है। यह समझना भी जरूरी है कि पैसा कहां जा रहा है, किस तरह का credit लिया जा रहा है और कौन-से digital tools इस्तेमाल किए जा रहे हैं।
Trend 1: Interest Rates और Borrowing Costs पर ध्यान
Interest rate में बदलाव का असर savings, fixed deposits और loans जैसे कई financial products पर पड़ सकता है। इसलिए Personal Finance planning में interest rate environment को समझना उपयोगी है।
भारत में monetary policy और interest rates को समझने के लिए RBI की official information देखना सबसे बेहतर तरीका है।
जब interest rates में बदलाव होता है, तो उसका असर हर व्यक्ति पर एक जैसा नहीं होता। किसी borrower के लिए loan की cost महत्वपूर्ण हो सकती है, जबकि किसी saver के लिए deposit पर मिलने वाला interest ज्यादा महत्वपूर्ण हो सकता है।
| Financial Area | Interest Rate में बदलाव का संभावित असर |
|---|---|
| Savings Account | Interest income बदल सकती है |
| Fixed Deposit | नई FD की interest rate बदल सकती है |
| Floating Rate Loan | EMI या loan tenure प्रभावित हो सकता है |
| Fixed Rate Loan | असर loan agreement की terms पर निर्भर करता है |
अगर आपके पास home loan या कोई floating-rate loan है, तो केवल EMI देखना पर्याप्त नहीं है। Interest rate, outstanding principal, remaining tenure और total repayment को भी समझना चाहिए।
इसी तरह savings और investment को अलग-अलग financial goals के हिसाब से देखना जरूरी है। इसके लिए Asset Allocation क्या है यह समझना उपयोगी हो सकता है।
Trend 2: AI और Personal Money Management
Artificial Intelligence अब financial services में भी इस्तेमाल हो रही है। Data analysis, customer service, document processing, risk management और कई दूसरे कामों में AI और machine learning tools का उपयोग बढ़ रहा है।
व्यक्तिगत स्तर पर भी AI-based tools budgeting, expense analysis और financial information को समझने जैसे कामों में मदद कर सकते हैं।
AI Personal Finance में कैसे मदद कर सकता है?
- खर्चों को categories में समझने में
- Monthly budget organize करने में
- Financial data summarize करने में
- बार-बार होने वाले खर्च पहचानने में
- Financial concepts को आसान भाषा में समझने में
- कुछ routine tasks को automate करने में
लेकिन AI को automatic financial advisor समझना सही नहीं है। SEBI ने AI tools के बारे में यह बात सामने रखी है कि वे complex या client-specific financial situations को हमेशा सही तरीके से नहीं समझ सकते और sensitive information share करने पर data-security concerns भी हो सकते हैं।
इसलिए अगर कोई AI tool आपके financial data को analyze करता है, तो उसकी privacy policy और data usage को समझना जरूरी है। Investment या insurance जैसे महत्वपूर्ण निर्णय केवल AI की recommendation के आधार पर नहीं लेने चाहिए।
सरल नियम: AI को information और analysis के लिए इस्तेमाल करें, लेकिन अंतिम financial decision अपनी स्थिति, जरूरत और risk capacity को समझकर लें।
Trend 3: BNPL और Digital Credit
Buy Now, Pay Later यानी BNPL ऐसा payment या credit model है जिसमें ग्राहक किसी purchase का पूरा भुगतान तुरंत करने के बजाय बाद में या installments में कर सकता है।
Digital platforms ने credit और deferred payment को पहले की तुलना में आसान बनाया है। लेकिन सुविधा के साथ repayment obligation भी आता है। इसलिए BNPL को केवल “आसान payment option” समझना सही नहीं है।
Digital lending से जुड़े products में loan की वास्तविक cost, repayment schedule और applicable charges को समझना जरूरी है। RBI के digital lending framework में customer protection, disclosures, data और grievance redressal जैसे पहलुओं पर नियम मौजूद हैं।
BNPL लेने से पहले क्या देखें?
- कुल कितनी राशि वापस करनी होगी?
- Interest या अन्य charges कितने हैं?
- Late payment होने पर क्या शुल्क लगेगा?
- Repayment की अंतिम तारीख क्या है?
- क्या credit reporting लागू होती है?
- क्या पहले से कई BNPL payments चल रही हैं?
- क्या यह purchase आपकी repayment capacity के अंदर है?
BNPL या digital credit लेने से पहले lender और product की वास्तविक terms समझना जरूरी है। केवल “No Cost” या “Easy EMI” जैसे शब्द देखकर निर्णय नहीं लेना चाहिए।
Credit card में भी इसी तरह repayment discipline महत्वपूर्ण है। अगर आप credit card के Minimum Amount Due के बारे में समझना चाहते हैं, तो Credit Card Minimum Amount Due और बढ़ते कर्ज वाला लेख पढ़ सकते हैं।
Trend 4: Side Hustle और Income Diversification
Personal Finance में केवल खर्च और investment महत्वपूर्ण नहीं हैं। Income भी financial planning का एक बड़ा हिस्सा है। इसी वजह से side income और income diversification पर लोगों का ध्यान बढ़ा है।
आज freelancing, blogging, YouTube, consulting और digital products जैसे कई कामों के जरिए अतिरिक्त income बनाने के अवसर उपलब्ध हैं। AI tools ने कुछ कामों की शुरुआती लागत और operational workload को भी कम किया है।
AI Side Hustle में कहां मदद कर सकता है?
- Content research
- Writing और editing
- Basic design और media creation
- Data organization
- Bookkeeping जैसे routine tasks
- Repetitive कामों की automation
लेकिन AI किसी side hustle की सफलता की guarantee नहीं देता। किसी भी नए income source में demand, competition, skill, time और लागत को समझना जरूरी है।
Income Diversification का मतलब क्या है?
Income diversification का सरल मतलब है कि आपकी कमाई केवल एक source पर निर्भर न हो। उदाहरण के लिए किसी व्यक्ति की primary job के साथ freelancing income हो सकती है, जबकि किसी दूसरे व्यक्ति की salary के साथ छोटा digital business हो सकता है।
लेकिन हर व्यक्ति के लिए side hustle जरूरी नहीं है। किसी व्यक्ति के लिए skill development, existing income बढ़ाना, debt कम करना या savings मजबूत करना ज्यादा उपयोगी हो सकता है।
अगर आप passive और additional income के अलग-अलग तरीकों को समझना चाहते हैं, तो Passive Income Ideas in Hindi भी पढ़ सकते हैं।
इन 4 Trends का आपकी Financial Planning पर क्या असर है?
इन trends को देखकर तुरंत कोई financial product खरीदने या अपनी investment strategy बदलने की जरूरत नहीं है। इनका practical मतलब इससे ज्यादा सरल है।
- Interest rates समझें: अपने loans और deposits की terms को समय-समय पर देखें।
- AI को tool की तरह इस्तेमाल करें: लेकिन उसकी हर recommendation को अंतिम सत्य न मानें।
- Digital credit समझकर लें: BNPL या किसी भी loan में total repayment cost देखें।
- Income पर ध्यान दें: अपनी क्षमता और जरूरत के अनुसार additional income के अवसर तलाशें।
2026 में Personal Finance के लिए Practical Checklist
- अपने monthly income और expenses लिखें।
- Fixed और variable expenses अलग करें।
- अपने loans की interest rate और repayment terms जांचें।
- High-cost debt की वास्तविक cost समझें।
- Emergency fund की जरूरत पर विचार करें।
- Investment करते समय risk और time horizon देखें।
- BNPL और digital credit को free money न समझें।
- AI tools इस्तेमाल करते समय personal financial data की privacy का ध्यान रखें।
- Side income शुरू करने से पहले demand और required skill समझें।
- महत्वपूर्ण financial decision से पहले official documents पढ़ें।
क्या 2026 में Traditional Savings बेकार हो गई है?
नहीं। Savings account, FD और दूसरे traditional financial products अभी भी अलग-अलग financial goals के लिए उपयोग किए जा सकते हैं।
किसी व्यक्ति के लिए emergency money को liquid रखना जरूरी हो सकता है, जबकि long-term goals के लिए अलग financial products पर विचार किया जा सकता है।
इसलिए Personal Finance का उद्देश्य किसी एक product को सबसे अच्छा साबित करना नहीं है। उद्देश्य यह समझना है कि अलग-अलग financial goals के लिए money management कैसे किया जाए।
क्या AI से Investment पूरी तरह Automatic हो जाएगा?
AI financial analysis और automation में मदद कर सकता है, लेकिन investment decision केवल technology के भरोसे नहीं छोड़ा जाना चाहिए। Market risk, taxation, liquidity, investment horizon और व्यक्ति की financial situation जैसे factors भी महत्वपूर्ण हैं।
AI-generated information में error या incomplete context की संभावना हो सकती है। इसलिए महत्वपूर्ण investment decision लेने से पहले official documents और जरूरत पड़ने पर SEBI-registered professional की सलाह पर विचार करना बेहतर है।
क्या BNPL लेना हमेशा गलत है?
नहीं। BNPL को अपने आप में अच्छा या बुरा कहना सही नहीं है। इसका असर repayment terms, charges, affordability और उपयोग के तरीके पर निर्भर करता है।
समस्या तब हो सकती है जब व्यक्ति अपनी repayment capacity से ज्यादा credit लेता रहे या कई छोटे BNPL payments एक साथ जमा होते जाएं।
क्या Side Hustle जरूरी है?
नहीं। हर व्यक्ति के लिए side hustle जरूरी नहीं है। किसी व्यक्ति के लिए existing income बढ़ाना, skill development, debt repayment या savings मजबूत करना ज्यादा relevant हो सकता है।
Side income एक संभावित option है, कोई universal financial rule नहीं।
Personal Finance Trends 2026 से क्या सीखें?
2026 में Personal Finance का एक महत्वपूर्ण बदलाव यह है कि financial decisions technology और digital ecosystem से पहले की तुलना में ज्यादा जुड़े हुए हैं।
Interest rates borrowing और saving decisions को प्रभावित कर सकते हैं। AI financial information और routine tasks में मदद कर सकता है। BNPL और digital lending credit को आसान बना सकते हैं, लेकिन repayment obligations भी साथ लाते हैं। वहीं side income के नए तरीके income diversification के अवसर दे सकते हैं।
इनमें से किसी भी trend को देखकर जल्दबाजी में financial decision लेना जरूरी नहीं है। बेहतर तरीका है कि पहले अपनी income, expenses, debt, savings और financial goals को समझें और फिर उपलब्ध options की तुलना करें।
अक्सर पूछे जाने वाले सवाल
2026 का सबसे बड़ा Personal Finance Trend क्या है?
एक ही trend को सबसे बड़ा कहना उचित नहीं होगा। Interest rates, AI-based financial services, digital lending और income diversification जैसे कई बदलाव Personal Finance को प्रभावित कर रहे हैं।
क्या AI Personal Finance में मदद कर सकता है?
हाँ, AI budgeting, data analysis और routine financial tasks में मदद कर सकता है। लेकिन महत्वपूर्ण financial decisions के लिए AI की जानकारी को verify करना जरूरी है।
क्या BNPL एक Loan है?
BNPL product की संरचना के आधार पर यह deferred payment या credit arrangement हो सकता है। इसलिए इसके terms, charges और repayment obligations को पढ़ना जरूरी है।
क्या Side Hustle से financial security बढ़ सकती है?
Additional income किसी व्यक्ति की financial position में मदद कर सकती है, लेकिन इसकी कोई guarantee नहीं है। Income source की stability, खर्च और समय की उपलब्धता को भी ध्यान में रखना चाहिए।
क्या Interest Rate कम होने पर Loan लेना हमेशा फायदेमंद होता है?
नहीं। Loan की interest rate के साथ processing fee, tenure, total interest, EMI और आपकी repayment capacity को भी देखना जरूरी है।
आगे पढ़ें
निष्कर्ष
Personal Finance Trends 2026 को समझने का मतलब किसी नए financial product के पीछे भागना नहीं है। असली जरूरत है कि आप interest rates, digital credit, AI tools और income opportunities को समझें और फिर अपनी financial स्थिति के अनुसार निर्णय लें।
Technology पैसे को manage करना आसान बना सकती है, लेकिन financial discipline, सही जानकारी और अपनी repayment capacity को समझना आज भी उतना ही जरूरी है।
